
MARKET BRIEF
Bali Hotel | H1 2026
Bali Hotel | H1 2026
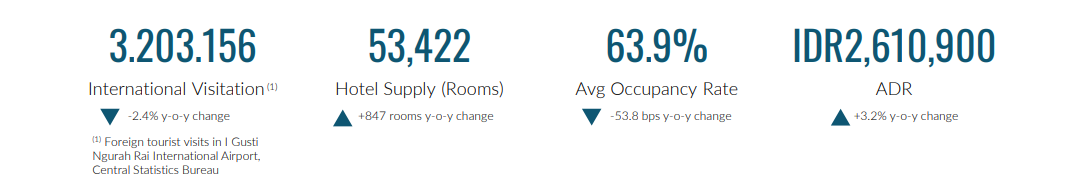
Bali’s accommodation market recorded notable supply growth in H1 2026, with eight new properties adding approximately 340 rooms, primarily concentrated in Ubud and Uluwatu. Despite this growth, hotel performance softened as occupancy declined amid seasonal demand patterns and heightened geopolitical tensions, which may affected travel preferences. ADR, however, remained resilient, although the gain was insufficient to offset weaker occupancy, resulting in lower RevPAR. Looking ahead, the continued development of five-star properties is expected to further strengthen Bali’s positioning in the luxury hospitality segment, while a recovery in travel demand could support hotel performance in H2 2026.
MARKET BRIEF
Jakarta Hotel | H1 2026
Jakarta Hotel | H1 2026

In the first half of 2026, Jakarta’s hotel market experienced a notable shift in supply dynamics, with room inventory increasing by 139 rooms compared with H1 2025. New opening, rebranding initiative, and hotel closures reshaped the competitive landscape, reflecting ongoing changes at both the operational and asset levels amid evolving market conditions. Meanwhile, demand continued to diversify beyond government-related business toward corporate, leisure, FIT, family, weddings, and private events. Upscale and luxury hotels remained relatively resilient, supported by stronger RevPAR and room-rate performance, higher-spending guests, and solid corporate and leisure demand, despite continued occupancy pressure. Overall, the market continued to move toward a more diversified demand base, while property repositioning reflected efforts to enhance asset competitiveness and adapt to changing demand patterns.
MARKET BRIEF
Jakarta Hotel | H2 2025
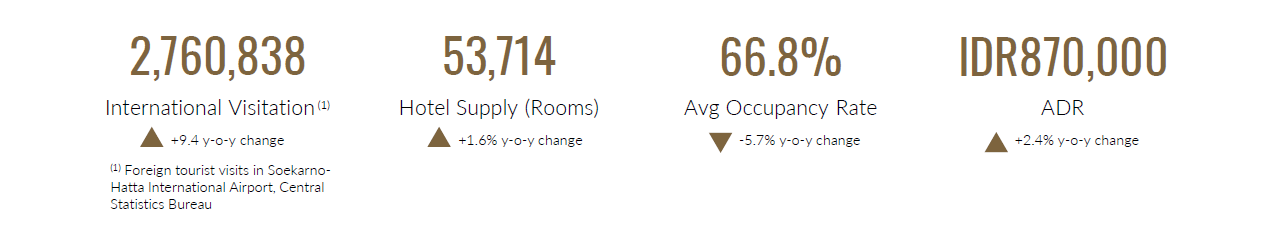
Jakarta’s hotel market in the second half of 2025 experienced a gradual but uneven recovery, supported by additional supply and improving demand from the return of MICE activity and business travel, particularly from Asia. However, overall performance remained under pressure as occupancy levels declined. Looking ahead, the Jakarta hotel market outlook for 2026 remains cautiously optimistic, with demand expected to continue recovering despite increasing competition from new supply. The government segment is likely to remain uncertain and limited, while the corporate and individual segments are expected to stay relatively stable.
MARKET BRIEF
Jakarta Hotel | H1 2025
Jakarta Hotel | H1 2025

The Jakarta hotel market in the first half of 2025 faced a challenging period, largely driven by government budget efficiency and the decline of MICE activity. Even though there’s been a slight increase in international visitor arrivals and offline events (concerts, sports and community activities), it hasn’t offset the overall negative trends. The Ramadhan season in March also contributed to the lower demand, with business activities seeing a modest slowdown during the first quarter. Adaptive strategies such as focusing on domestic demand and capitalizing on event-related opportunities might help the market into the end of 2025.
MARKET BRIEF
Jakarta Hotel | H2 2024
Jakarta Hotel | H2 2024

The performance of Jakarta's hotel industry remained robust in the second half of 2024, following a strong showing in the first half of the year. The government's mid-November announcement of a 50% budget reduction for state civil servants (ASN) had minimal impact on the city's hotel sector. While hotels that rely heavily on government business were somewhat affected, those with more diverse markets felt less of a strain. Looking ahead to the first half of 2025, hotel performance is projected to continue improving gradually despite uncertain global economic conditions and the government's plan to further reduce the budget for official travel.
MARKET BRIEF
Jakarta Hotel | H1 2024
Jakarta Hotel | H1 2024

At the beginning of the first half of 2024, the Jakarta hotel industry experienced slower growth compared to the latter half of the year. The slowdown was primarily due to the Ramadhan season, during which government and business activities typically quiet down. However, the market remained strong as MICE activities resumed after Eid, and numerous musical events were hosted in the city during this period. Unlike previous years, the General Election held in the first half of 2024 had minimal impact on occupancy rates in Jakarta’s hotel market. Hotel performance is projected to continue improving until mid-Q4 2024.
Subscribe below to be sent the report. Do contact us should you have further inquiry.